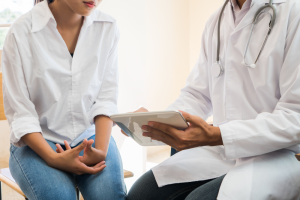

When applying for term life insurance in South Africa, you may be required to undergo a medical examination. This forms a key part of the underwriting process – a vital step in determining your cover terms, premium rates, and long-term policy viability.
Why is it important to go through with our medical underwriting? Our underwriting process includes evaluating factors such as age, gender, lifestyle, and pre-existing conditions. These details help us tailor policies that suit your specific needs while ensuring fairness and sustainability.
A well-underwritten policy offers peace of mind to policyholders, knowing their beneficiaries will receive the promised benefits. Our underwriting process, which includes medical exams, plays a pivotal role in determining the terms of your coverage and ensuring that both you and the insurer are protected. After underwriting, conducting medical exams is essential for several reasons, which are explored below using health statistics, adult mortality rates, and the risk of cancer, among other factors.
Accurate Risk Assessment
Medical exams provide insurers with a clear and objective picture of your current health status. This typically includes checks like blood pressure, cholesterol levels, and medical history through physical exams and lab tests. This data helps place applicants into risk categories (e.g., Standard, Preferred), which directly influence your premium.
Without accurate health information, you may be misclassified—leading to unfairly high premiums or underpricing that could affect future claims or policy stability.
Tailored Premiums and Policy Terms
Medical exams ensure that the premiums you pay are fairly priced based on your health. If you’re in good health, you’re more likely to receive better rates. Even if you have a condition, accurate information helps the insurer offer realistic, responsible cover.
Example: A person with controlled high blood pressure may qualify for better rates than someone with untreated hypertension, because the condition has been verified and shown to be managed.
Identification of Undiagnosed Conditions
You might not be aware of certain conditions – like diabetes, high cholesterol, or hypertension – until they’re picked up during your medical screening.
Why this matters: Discovering these issues allows insurers to adjust your cover appropriately, while also giving you the opportunity to seek preventative care or treatment that can improve your long-term health.
Legal and Ethical Compliance
Accurate medical underwriting ensures that policies are issued in line with South African legal and ethical standards. It helps verify the information provided during the application process and prevents unintentional misrepresentation.
Key takeaway: Medical verification protects both you and your insurer from potential disputes or claim denials later on.
Long-Term Policy Viability
Medical exams help insurers maintain the financial stability of their products. By setting premiums that reflect verified health risks, insurers can continue to pay out legitimate claims without putting the broader risk pool – or their business – at risk.
Final Thoughts
A well-underwritten policy, backed by accurate medical data, offers peace of mind. It ensures your loved ones will receive the full benefits they’re entitled to, and that your policy remains a responsible, sustainable investment in their future.